Blog
What a wholesale lending platform lets you say yes to
By NETSOL Technologies Inc. , on October 22, 2026
A dealer request is a better test of value than a low bid
Table of Contents
Subscribe to our newsletter
Share this Blog:


A dealer group asks for a used-stock funding line across several sites. Your credit team likes the opportunity, but the requested terms differ from the lines you already run. Operations must find out whether the platform can handle them before anyone can quote.
A wholesale lending platform earns its place when it helps a lender act on a sound dealer opportunity. Judge the value it delivers with a recent request you could not serve quickly. Ask what needs vendor work and what support follows.
Test a wholesale lending platform with a real dealer request
A feature list tells you what exists today. A recent dealer request shows what happens when you need something different. Choose one that credit would consider, then trace it from approval through to a live funding line. This keeps the discussion on business you might win.
For example, the dealer may want a funding structure your lines do not offer or curtailment terms that differ from your standard. A curtailment is the paydown scheduled against each funded unit. Credit can approve the dealer whilst a platform change holds up the line. Ask every vendor, including us, to show which parts your team can set up and test and which require a release.
The Finance & Leasing Association's July 2026 asset-finance figures report that its members' used-car new business rose 29% from a year earlier (Finance & Leasing Association, 2026). That is business asset finance, not a floorplan measure, but it shows where some finance demand is moving. Your own dealer requests will show where yours is.
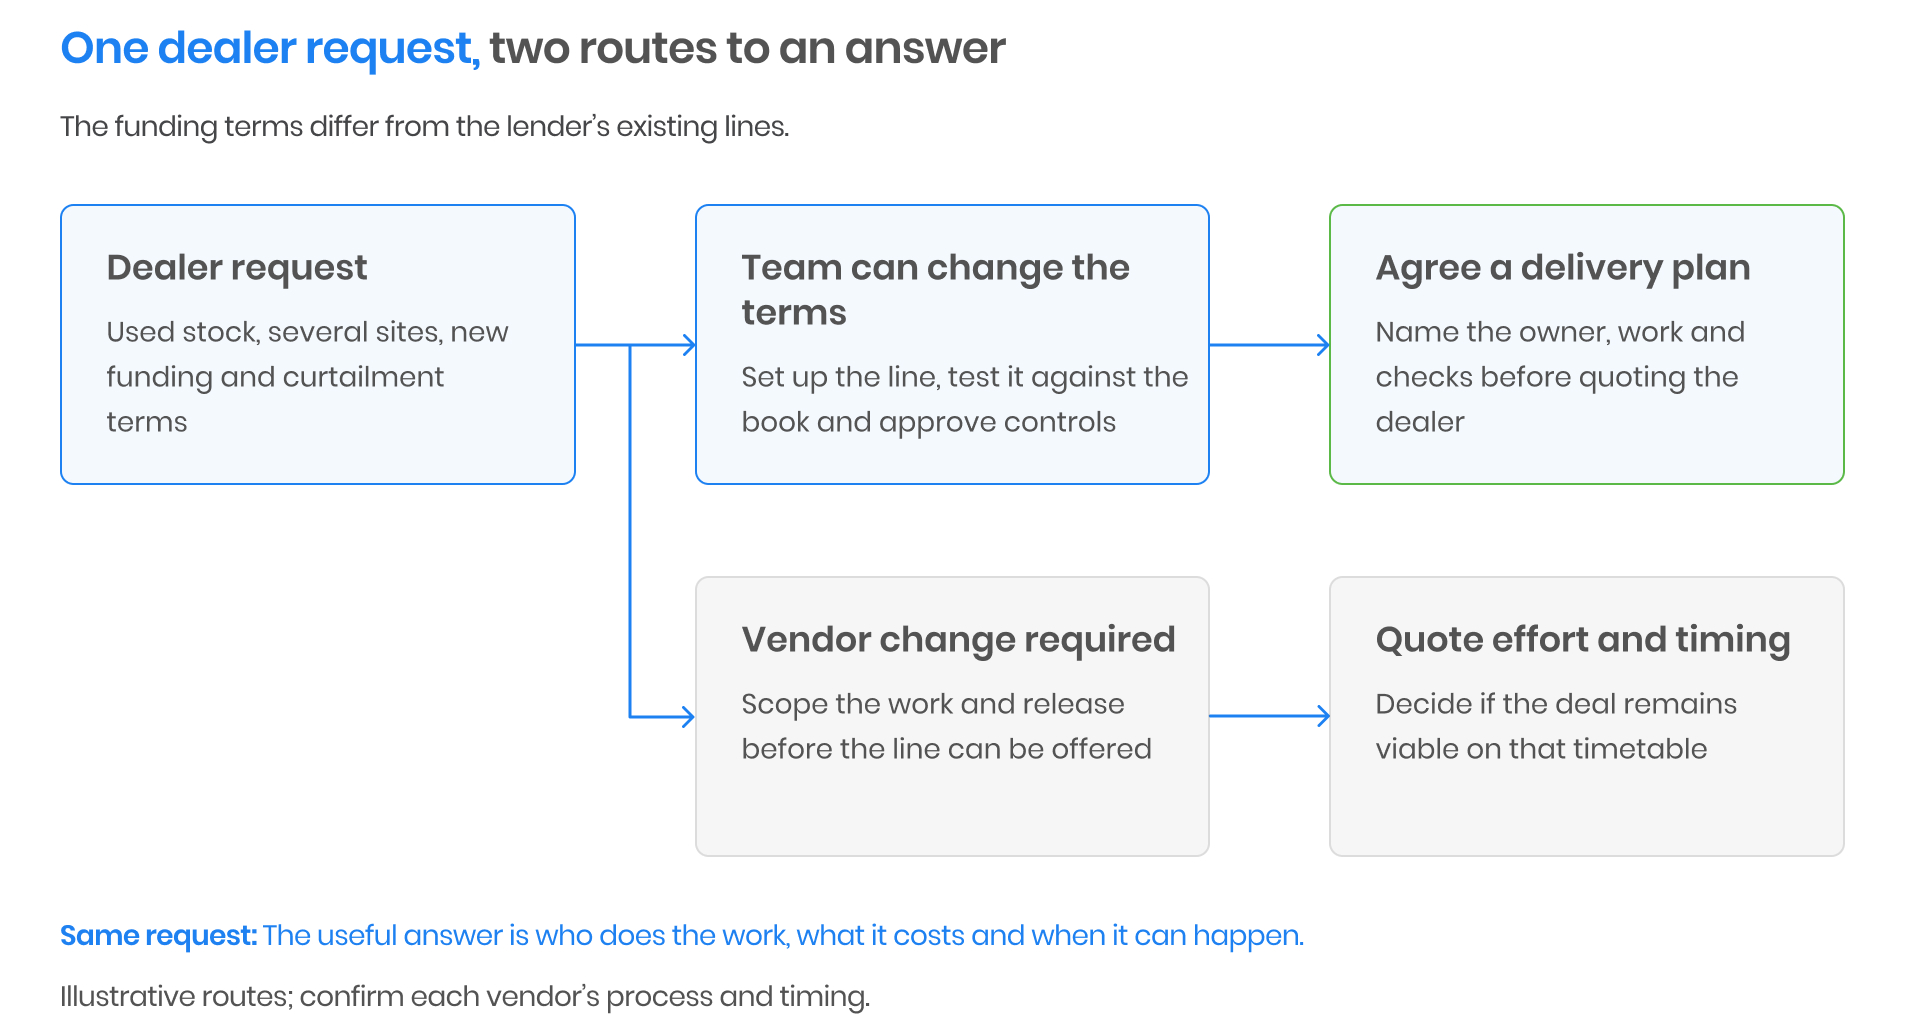
Figure: Take one dealer request through both routes. The useful answer is who does the work, what it costs and when the line could be offered.
Ask who has to change what
The question is not simply whether the software has a field for a new line. The lender needs to know who can change the funding terms, how the change is tested against its existing book and what happens if it fails. A demo should use your request. The measure that matters is how long the lender takes to offer a line once credit has approved it.
If the lender's team can make the change, ask what controls and approvals apply. If it needs a vendor release, ask for a realistic lead time, cost and test plan. Either answer can be workable. Know that before a dealer is waiting.
A lower fee says little about the effort needed to add a new line. Include that effort, the likely delay and the people required in the selection case.
Support quality matters when the next opportunity arrives
Post-go-live support is part of this test. When credit has approved a new dealer line but operations cannot put it into use, who helps the team move forward? Ask for a responsive support route, the people who know the wholesale product and an example of how a similar change was handled.
The question is whether support helps you act on a viable opportunity. Our article on wholesale finance implementation and support examines the wider post-go-live relationship. The wholesale finance guides offer more review questions.
What this means for wholesale finance leaders
- Choose a recent dealer request that your team could not serve quickly.
- Ask each vendor who would set up, test and approve the required change.
- Include the time, cost and support effort in the value comparison.
Questions about wholesale platform value
How do you compare value rather than price between two platforms?
Give both vendors the same dealer request. Ask each to show who would make the change, what testing it needs, what it would cost and when the line could be offered. Compare those answers alongside the quoted price.
What makes a wholesale platform able to follow a market?
A wholesale platform can follow changing dealer demand when the lender's own team can set up and test new terms, such as a different funding structure or curtailment schedule, without a vendor release. Ask each vendor to show this on one of your real dealer requests.
The right bid helps you take the next opportunity
The cheapest platform is not necessarily the one that leaves a lender best placed to grow. A decision based only on current features can miss the work that begins with the next dealer request. Put that request through every shortlisted platform. A platform moves your business forward when it helps you take on a viable request within a workable time and cost. The comparison will show which option does that, and with whose support.
NETSOL's Transcend Finance wholesale finance module covers floor planning, dealer and inventory financing, group credit limits and configurable internal controls. Put the same dealer request through our module as through any other vendor. Which of your last three commercial requests would you use to test your next platform?
Modernise your asset finance operations with NETSOL
Related blogs
Blog
What a wholesale lending platform lets you say yes to
Blog
NETSOL is ready for Palm Desert: Transcend Finance to take center stage at ELFA 2026
Blog