Blog
UK automotive finance software and the value of experience
By NETSOL Technologies , on September 24, 2026
How lenders can assess whether global and UK experience will support their own book
Table of Contents
Subscribe to our newsletter
Share this Blog:


An automotive finance platform may look convincing in a demonstration. The harder test starts when a lender maps its own products, processes and reports. Experience is useful when it helps the project team understand those needs and plan the work.
For a UK lender choosing automotive finance software, two kinds of evidence matter. Global experience shows whether a provider can support different finance products and operating models. UK experience shows whether that knowledge has been applied in the lender's own market.
Relevant experience is easier to assess than longevity
Four decades of experience describes the work a team has seen. Its value comes from the lending models, products and market needs that the work covers.
A lender can test that relevance with practical questions during selection. Has the provider supported retail and wholesale finance? Has it worked with captives, banks and independent lenders? Which parts of previous projects were reused, and which required local work?
A mature market may test long contracts and detailed reports. A newer market may test local changes. A captive may need dealer programmes, whilst a bank may focus on governance. The provider should test each need with the lender.
The aim is not to find an exact copy of your book. It is to see whether previous work helps the team ask better questions early.
Global experience should provide a reusable starting point
One example is NETSOL Technologies programme for a global automotive captive. The client was preparing to replace leasing and wholesale finance technology across 11 markets in Asia-Pacific and South Africa. Work began with a live model office in Singapore before country-level rollout.
The model office gave the client a common starting point. Teams reviewed core processes and held workshops for Korea and Australia to find local gaps. This clarified the plan. The source does not say all 11 markets were live.
The lesson is practical. Start with a tested base, then identify the products, workflows, system links and reports that need local decisions.
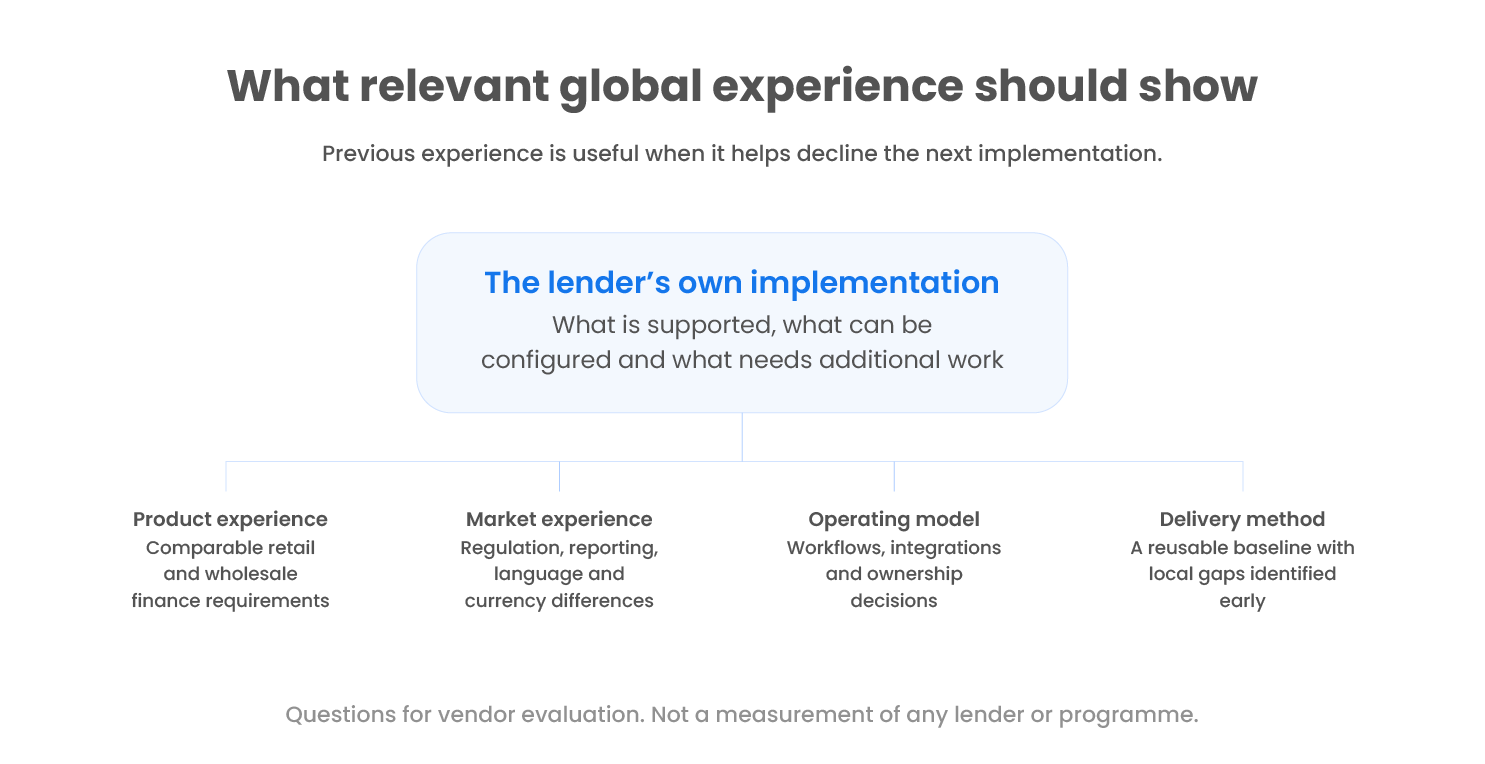
Relevant experience helps a lender separate reusable capability from local implementation work.
UK experience shows whether the provider understands the market
Global reach does not replace UK experience. A UK lender should also look for evidence from local institutions, products and delivery teams.
In January 2026, Northridge Finance went live with Transcend Finance. Northridge is a division of Bank of Ireland UK. It provides personal and commercial asset finance across the UK and specialises in motor finance.
Northridge chose the platform to support wholesale dealer funding and give dealers more flexibility and easier access. This gives UK automotive lenders a current, named example using Transcend Finance.
There is also evidence of sustained UK use. In April 2026, NETSOL announced that a tier-one multinational bank in the UK renewed its agreement for the finance and leasing platform. The relationship spans more than 15 years and supports retail and wholesale finance operations.
This second example is broader than motor finance, but it shows durability at scale in the UK asset finance market.
Together, these examples show a current deployment at a UK motor finance lender and long-term use at a large bank. They give a lender concrete evidence to test.
Ask what NETSOL learnt about local data, controls, dealer onboarding and change after go-live, then test how that learning will support your project.
Ask how UK automotive finance software experience applies to your book
Configuration uses controlled settings to change products, rules or workflows. Some needs may still require development or a new system link.
Ask the provider to show one of your products. The team should explain what works today, what can be configured and what needs more work. It should show how UK and global lessons shape the plan.
What this means for UK lending leaders
- Verify experience with comparable UK products, lender types and operating requirements.
- Verify existing capability, configuration and additional work using a real product.
- Verify how previous UK delivery will improve the plan, ownership and controls.
Our automotive finance guides cover more choices involved in selecting and introducing finance technology.
Questions UK lenders ask about global platforms
What should a UK lender look for in an automotive finance software provider?
Look for global experience and UK delivery. Ask for examples involving similar products and operating models, then test the platform with one of your products.
Does a global automotive finance platform need a separate UK version?
Not necessarily. A shared platform can support UK products, rules, workflows and reports. The lender should confirm what is standard, what can be configured and where local development or integration is needed.
Relevant experience should make the next implementation clearer
Useful experience gives the lender a better starting point. Global work can show how a platform adapts across markets. UK work can show how that capability performs closer to home. The plan should be built from both, and success still depends on clear local choices.
Transcend Finance brings origination, contract management, servicing and wholesale finance into one automotive finance software platform. If you are assessing a new platform, discuss your requirements with our team.
Modernise your asset finance operations with NETSOL
Related blogs
Blog
Wholesale finance implementation that lasts beyond go-live
Blog
NETSOL heads to Digital Dealer 2026: Bringing Transcend Retail to Detroit
Blog